The Hidden Side of Condo Financing: What Buyers Need to Know
When you’re buying a condo, it’s easy to focus on the unit itself: the location, layout, monthly condo fee, and whether the home checks all the boxes.
But there’s another piece of the puzzle that can have a major impact on your purchase: how the condominium itself is viewed by the lender.
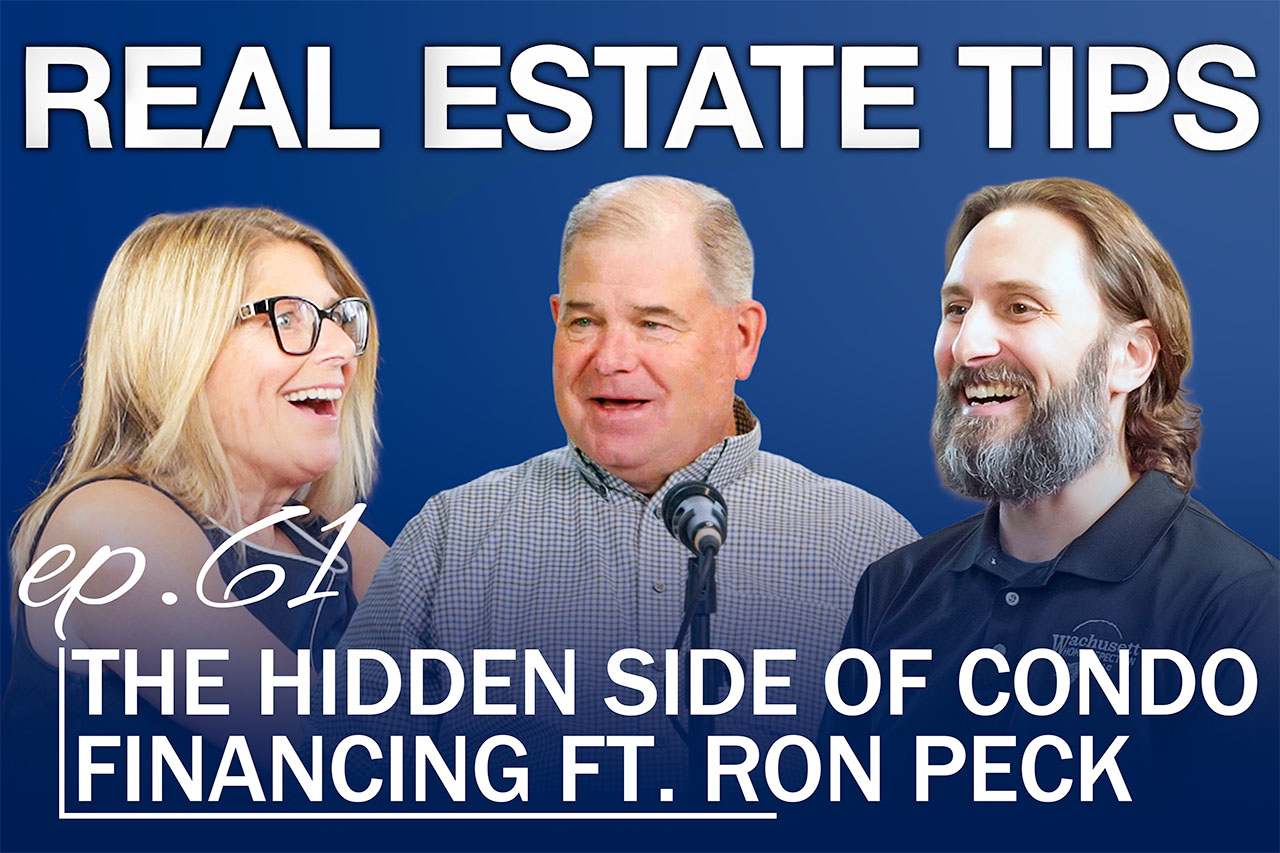
In Episode 62 of Real Estate Tips with Lana & Mark, we sit down with mortgage professional Ron Peck to talk about the hidden side of condo financing and what buyers should understand before they make an offer.
It’s Not Just About the Buyer
When you apply for a mortgage, your finances, income, credit, and assets are obviously important. But when you’re purchasing a condominium, the lender may also need to take a closer look at the condo association and the property itself.
That can include things such as the association’s financial health, insurance, ownership structure, pending issues, and other factors that can affect whether a particular loan can move forward.
In other words, you may be financially qualified to buy a condo, but that doesn’t necessarily mean every condo will qualify for every type of financing.
Why Condo Buyers Should Start the Conversation Early
This is one reason it’s important for condo buyers to work with their lender early in the process—not just to determine their budget, but to understand what may be involved once they find a property.
A condo that looks perfect on paper can present financing questions once the lender begins reviewing the property and association.
Getting ahead of those questions can help buyers better understand their options and avoid surprises later in the transaction.
What About the Condo Association?
One of the biggest differences between purchasing a single-family home and a condo is that you’re buying into a larger community.
The lender may need information about the condominium association and its finances before determining whether the property meets the requirements for the loan.
That means buyers should not look only at the monthly condo fee. It’s also worth understanding what that fee covers, the overall condition of the association, and whether there are any known financial or structural issues that could affect the property.
Questions Worth Asking Before You Buy
If you’re considering a condo, here are a few things to discuss with your real estate agent and lender:
- What documentation will the lender need from the condo association?
- Are there specific financing requirements for this property?
- Are there any pending assessments or major projects?
- How financially healthy is the condo association?
- What does the monthly condo fee cover?
- Are there any insurance or ownership considerations that could affect financing?
- Could the property qualify for the type of mortgage you’re planning to use?
The answers can vary from one condominium to another, which is why it’s important not to make assumptions.
Listen to Episode 61
There’s much more to the story, and Ron Peck helps break down the details buyers may not think about when financing a condo.
Whether you’re a first-time buyer or you’ve purchased real estate before, understanding the financing side of a condo purchase can help you approach the process with fewer surprises.
Tune in to Episode 61 of Real Estate Tips with Lana & Mark: “The Hidden Side of Condo Financing” featuring Ron Peck.
https://www.youtube.com/watch?v=xD1xjkbFVOc
Check out My Little Black Book for a list of my trusted service professionals.
I am your local real estate expert Making Realty Dreams Reality. Give me a call at 978-855-9112 or fill out this contact me form to get started on your homeownership journey.


© 2022 Coldwell Banker Residential LLC
© Coldwell Banker 2023 – 2024. All Rights Reserved. Coldwell Banker and the Coldwell Banker logo are trademarks of Coldwell Banker Real Estate LLC. The Coldwell Banker® System is comprised of company owned offices which are owned by a subsidiary of Anywhere Advisors LLC and franchised offices which are independently owned and operated. The Coldwell Banker System fully supports the principles of the Fair Housing Act and the Equal Opportunity Act.
